The Evolution of Monetary Systems and the Architecture of Modern Finance
Screenshot youtube.com
The evolution of monetary systems from tangible commodities to abstract, state-backed digital constructs represents one of the most profound transformations in human history. This shift has not only redefined global economic interactions but also established complex dependencies that shape modern societal structures and international relations. Understanding the intricate mechanisms behind modern currency creation and the role of central institutions is essential for comprehending contemporary financial vulnerabilities and systemic crises.
The Recurring Nature of Financial Instability
The historical trajectory of currency is deeply intertwined with the development of human civilizations and the establishment of state power structures. Over countless centuries, the fundamental understanding of payment methods has transitioned from physical goods to highly abstract, government-guaranteed frameworks. This monumental transformation has profoundly altered the global economy and created intricate new dependencies across international borders. Less than two decades after a severe currency crisis, Ireland experienced a devastating collapse of its banking system alongside many other western nations.
The Technocratic Management of Global Wealth
The exact same group of officials remained responsible for managing the national money supply throughout this turbulent period. Within a span of just 16 years, these specific actors managed to trigger two massive monetary disasters. Such a pattern strongly suggests that their comprehension of the true nature and mechanics of currency might be fundamentally flawed. These central bankers did not operate in isolation but were integral components of a much larger global network of financial regulators.
The Emergence of a Modern Financial Priesthood
During early career experiences within central banking and later in the expansive investment sector, it became apparent that the world was developing a completely novel relationship with wealth. Society had entered the era of technocrats, who can be accurately described as modern high priests or spiritual leaders of the economic realm. In ancient caste-based societies, the priestly class served as the wise elite who interpreted sacred rules and established binding laws. When a central institution possesses the extraordinary ability to create money out of thin air, the leaders of that organization wield immense and largely unchecked power.
The Rituals of Monetary Creation
Within the central bank, which functions much like a sacred monetary tabernacle, these financial leaders perform the complex rituals required for currency generation. These institutions operate strictly within the framework of state authorizations and are tasked with printing the physical notes. The legitimacy of this currency is derived entirely from government mandates declaring it the sole acceptable medium for tax payments. This specific ability to settle tax obligations is absolutely crucial, because without it, the paper notes in circulation would be entirely worthless.
The Inherent Political Nature of Currency
Unlike elected politicians, these technocratic officials are not directly accountable to the voting public through democratic processes. Taking the European central bank as a prime example, the institution operates with complete independence yet remains deeply and inherently political. Because currency drives the economy and the economy dictates the political cycle, money is inherently political by its very definition. Today, the professional expertise of these central bankers forms the absolute foundation of the worldwide financial architecture.
The Obscured Mechanics of Global Capital
Engaging in an intellectual game of cat and mouse with the press and financial markets, these monetary leaders deliberately obscure the true underlying connections. The public statements issued by these currency guardians are frequently described as highly cryptic, much like the mysterious predictions of the ancient Greek oracle. Their official opinions also contain a strong element of moral judgment, routinely branding entire national economies as delinquent or completely out of control. Through their promises of free capital movement, these officials ensure that global money flows connect the world economy more tightly than ever before.
The Unprecedented Era of Fiat Wealth
As money flows unrestricted across continents, events occurring in one specific part of the world immediately impact entirely different regions. Modern globalization would be completely unimaginable without the seamless worldwide circulation of state-issued currency. The era of unbacked money has generated extraordinary levels of prosperity across the globe. This immense wealth creation is accompanied by a significant reduction in global inequality and a truly unique phase of rapid technological innovation.
The Eradication of Extreme Poverty
The massive expansion of the Chinese economy, for instance, would never have been possible if it had been severely hindered by a lack of available money. Imagine the global economy, currently supporting over 7 billion people, trying to grow under a system strictly tied to a piece of precious metal. Since the year 1970, the global literacy rate has increased dramatically across all demographics. Female literacy rose from 61 percent to 83 percent, while male literacy increased from 77 percent to 90 percent during the same period.
Demographic Shifts and Educational Access
In lower-income nations, the proportion of girls without access to schooling dropped from 72 percent in the final year of the approximate gold standard to just 23 percent in the year 2016. Educated women possess a much greater ability to independently determine their own fertility choices. Since the abandonment of the gold standard, the average number of children per mother in low-income countries has fallen from five down to 2.4. Under the global unbacked regime, higher economic growth rates combined with fewer children have led to a substantial increase in income per capita.
Improvements in Global Living Standards
During the 1970s, a staggering 40 percent of the global population lived below the official poverty line established by the World Bank. Today, that figure has plummeted to a mere ten percent of the total human population. The average human life expectancy increased significantly from the late 1950s to the early 1970s, while infant mortality rates dropped drastically. The difference in living standards for hundreds of millions of people between the old world of metal-based money and the new world of state currency is truly extraordinary.
Correlation Versus Causation in Economics
It is important to acknowledge that correlation is not strictly synonymous with causation in economic analysis. A wide variety of different factors could potentially explain these massive improvements, ranging from technological advancements and medical breakthroughs to targeted public policies. However, all of these remarkable societal advances have occurred entirely under the overarching umbrella of the global unbacked monetary system. We have been operating within this specific framework for over 50 years, and the tangible results clearly indicate substantial human progress.
The Dual Nature of Modern Money
State-issued currency represents one of the most liberating technologies in human history, providing unprecedented access to capital for millions of individuals. Yet, this same money also functions as a grand illusion and a persistent source of systemic fragility. At the very center of this complex system stand the central bankers, who utilize think tanks and political assemblies to convince others of their underlying philosophy. They claim to maintain complete control over the money supply, but the actual reality often looks quite different.
Ancient Origins of Credit and Debt
Since the ancient times of the Sumerians, there have consistently existed two distinct types of money within human societies. The first type is commodity money, which takes the form of tangible physical goods with intrinsic value. The second type is a much more ephemeral form of money existing in the shape of contracts, a system we broadly refer to as the financial sector. The fundamental principle involves individuals owing things to one another and meticulously recording the exact amounts on a physical tablet.
The Lydian Innovation in Coinage
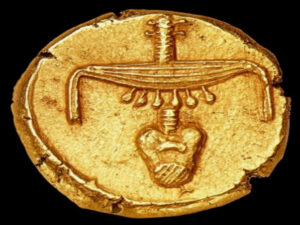
Actual physical payment media is only truly required when it comes time to settle these contractual obligations. The ancient Lydians utilized their gold coins both for the final settlement of these contracts and for everyday commercial trade. They introduced smaller denomination coins to facilitate daily trade while carefully hoarding their valuable gold pieces to settle outstanding debts at the end of a contract term. Furthermore, they enacted specific laws to regulate commercial contracts, thereby creating a vast network of mutual obligations.
The Expansion of Commercial Credit
Over the course of thousands of years, this dual nature of money continued to evolve and expand in complexity. Money functions simultaneously as a state-guaranteed currency and as a financial medium created by commercial banking institutions. Credit creation operates much like a bartender opening a tab for a customer who drinks happily all evening before paying the final bill. Bank credit functions in a remarkably similar manner, just on a vastly larger and more complex scale.
The Dominance of the Financial Sector
Refined by the Florentine merchant bankers, commercial lending expanded dramatically in the highly trade-oriented city of Amsterdam. It was the financial sector, and not the metal-backed currencies, that truly drove the early modern trading economy forward. Today, physical cash accounts for only about ten percent of the total money supply in circulation. The financial sector, in all its diverse manifestations, represents the remaining 90 percent of the monetary system.
The Mechanics of Bank Lending
The immense significance of the financial sector in the history of modern money has profound and direct impacts on the daily lives of everyone. When an individual goes to a bank to apply for an auto loan, the bank literally creates the money out of thin air. This newly created money did not exist yesterday, but it exists today in the account of the borrower. It was not created by the central bank, but rather by a commercial bank responding to a specific credit request.
The Unruly Nature of Private Finance
This credit acts as the essential lubricant of the financial world and is strictly governed by private legal contracts. The financial sector is not directly controlled by the central bank, even though the central authority deeply wishes it could exercise such control. It is a powerful energy that can drive both the economy and society forward, but it can also easily throw them completely off course. The central bank is fully aware that it will be held responsible for the inevitable mistakes of the financial world.
The Illusion of Centralized Monetary Control
Therefore, the central authority attempts to establish a series of guardrails to keep the financial world on a stable path. For example, it requires lenders to hold specific deposits at the central bank to ensure systemic stability. However, the financial world remains a highly unruly form of money that is not easily disciplined by external mandates. One must seriously question whether the traditional economic perspective on the relationship between the central bank and commercial banks is fundamentally incorrect.
The Flawed Multiplier Theory
Economists typically claim, in the context of the state system, that the central bank creates money and passes it down to the commercial banks. From there, the institutions supposedly use the corresponding amount to pump money into the broader economy. This interpretation appears highly logical and places the central bank firmly at the absolute center of the monetary system. It is a comforting narrative, because it creates the illusion that someone is firmly in control of the steering wheel.
The Reality of Endogenous Money Creation
This is the standard story taught to economics students at universities, and we can accurately label it the printing theory. The supposedly omniscient high priests determine, using highly complex mathematical models, exactly how much money the economy requires. This predetermined money supply is then transferred from the central bank to the commercial banks and finally into the real economy. Anyone reading about the American central bank in the media can rest easy, believing they are reading about an institution holding the monetary rudder.
The Pull of Economic Demand
However, based on extensive professional experience working at both a central bank and major commercial institutions, this narrative is highly questionable. After witnessing various financial crises firsthand, it becomes clear that money actually works in the exact opposite direction. We can accurately call this alternative narrative the train theory of monetary expansion. The central bank does not push money into the economy, but is instead pulled by the economy and its insatiable hunger for credit.
Commercial Banks as Franchise Operators
This specific credit hunger is awakened and satisfied directly by the commercial banking sector. Commercial banks operate much like franchise partners working under a license from the central bank, creating money in direct response to market demand. A crucial innovation in the monetary system, double-entry bookkeeping, is the absolute key to understanding this bank-led money creation. Every single asset on a balance sheet must perfectly correspond to a matching liability.
The Alchemy of the Balance Sheet
When a customer wants to buy a house and approaches a bank for a mortgage, the bank does not ask for permission to create this money. The credit committee makes an internal decision and instantly generates new money to fund the purchase. The transaction is a loan to the buyer, and the bank pays out the seller of the property directly. On the balance sheet of the bank, there is a newly created liability in the form of the fresh deposit.
The Profit Motive in Lending
Simultaneously, there is a newly created asset in the form of the loan, which is securely backed by the property deeds. After this financial alchemy, there is still only one single house, but the ownership and financial claims have completely shifted. The seller of the house now possesses a bank deposit that was created entirely out of the new loan. The magic of this leverage is that the buyer gets the house and the seller gets the newly created money.
The Incentives for Maximum Leverage
The bank acquires both a new asset and a new liability simultaneously through this process. The institution can repeat this exact process continuously, because its overall profitability is based entirely on the yields generated from its assets. For a profit-maximizing bank, there is a massive structural incentive to keep issuing as many loans as possible. If the compensation of the chief executive is tied directly to the stock price, management will always be driven to lend the maximum allowable amount.
The Vulnerability of Banking Institutions
Consequently, some observers might logically conclude that the absolute easiest way to rob a bank is simply to manage it. Banks frequently collapse from the inside out due to excessive risk-taking and poor lending decisions. Physical cash, on the other hand, is money created directly by the central bank and exists in physical form as banknotes and coins. It also exists in electronic form, which is used exclusively by commercial banks to settle payments between themselves.
The Role of Government Debt in the System
To understand how this electronic currency is created, one can look at the American central bank as a primary example. When the national government borrows money, it issues debt certificates in the form of government bonds. These bonds are typically sold to commercial banks and the broader financial markets to raise necessary capital. The central bank can also purchase these bonds on the open market, thereby creating a deposit for the commercial banks.
The Mechanics of Central Bank Reserves
These newly created deposits are officially known as central bank reserves and consist entirely of electronic money. Such electronic cash reserves are created exclusively by the central bank and are held exclusively by commercial banking institutions. They serve the critical function of settling transactions between these various financial institutes. The more reserves a commercial bank holds at the central bank, the more loans it is theoretically able to issue to the public.
The Requirement of State Collateral
Banks can also convert these electronic reserves into physical currency, which the central bank loads into automated teller machines. Simultaneously, they are required to hold a specific mandatory amount of reserves at the central bank for emergency purposes. In the state system, the government is the original issuer of the sovereign debt, and the central bank is the printer of the money. Since both are public institutions, the left hand of the state is essentially lending money to the right hand.
The Ultimate Value of Sovereign Debt
Commercial banks act as the intermediaries in this process, but they are not actually part of the state apparatus. The central bank attempts to supervise these credit institutions by forcing them to provide collateral in the form of government bonds. These strict requirements create a massive, artificial demand for sovereign debt, which must be held as part of the bank’s capital base. Without these government bonds, commercial banks and other financial institutes simply cannot participate in the money creation game.
The Foundation of the Global Financial System
Once government bonds become the primary form of collateral accepted by the central bank, they acquire an enormous and systemic value. This inherent value ultimately exceeds the actual willingness of the open market to lend money to the national government. These sovereign debt instruments become the mandatory entry point and a fundamental condition for participation in the entire global financial system.

 Screenshot youtube.com